


DSCR Loan Florida
Ridge Street Capital is a direct private lender providing financing for rental property purchases in Florida, including long-term and short-term rental loans, as well as cash-out refinancing and rate-and-term refinances.
The program works for first-time investors and for operators scaling a portfolio. Rates start at 6.0%, loans close in 21 to 25 days, and borrowers qualify using property cash flow instead of personal income.
With experience funding rentals in Miami, Tampa, Orlando, Jacksonville and across Florida, Ridge Street offers industry-low rates and a process that is quick, easy and reliable from application to closing.
Florida DSCR Loan Highlights
- Qualification based on rental income, not tax returns
- Minimum DSCR: 1.0
- FICO score: 660
- Loan amounts from $55,000 to $2,000,000
- Up to 80% LTV on purchase, 75% on cash-out
- Single-family, multifamily 2-10 units, condos
- Interest rates starting at 6.0%
Why Choose Ridge Street in Florida?
Over 200
Funded Loans
$90M+
Loan Volume
21-25 Days
Avg. DSCR Closing Time
In 36 States
Including Florida
Track Record
Funded DSCR Loans in Florida
Funded and sample Florida deals from Ridge Street's underwriting desk
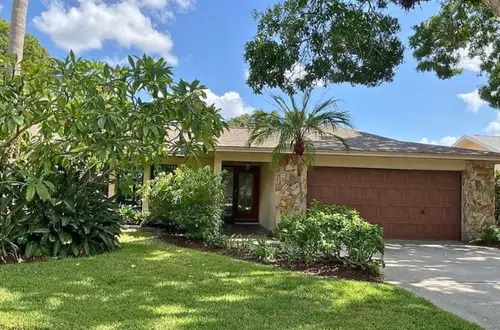
Seminole, FL
Loan amount
$538,000
Rate
6.875%
LTV
80%
Type
Purchase
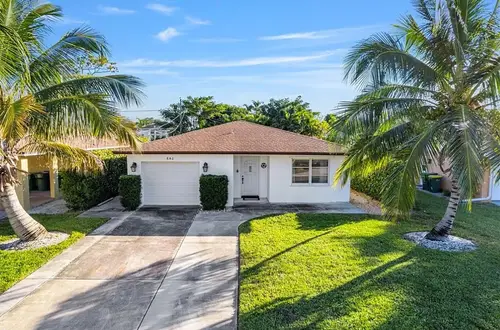
Naples, FL
Loan amount
$496,000
Rate
6.917%
LTV
80%
Type
Purchase
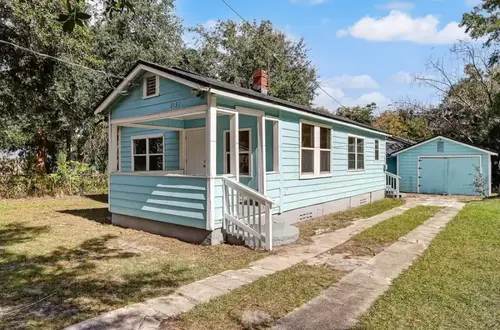
Jacksonville, FL
Loan amount
$86,000
Rate
7.63%
LTV
80%
Type
Purchase
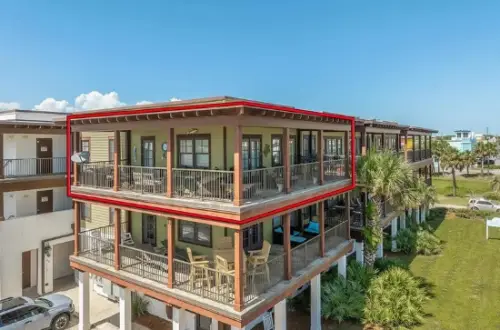
Saint George Island, FL
Loan amount
$396,000
Rate
7.025%
LTV
72.66%
Type
Purchase
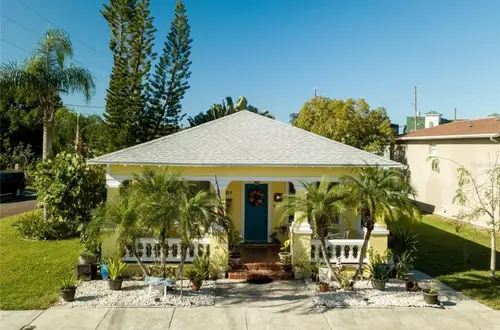
Tarpon Springs, FL
Loan amount
$408,000
Rate
6.93%
LTV
75%
Type
Refinance
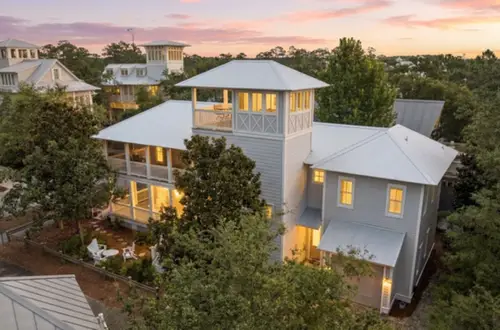
Santa Rosa Beach, FL
Loan amount
$1,385,700
Rate
6.158%
LTV
46.97%
Type
Refinance
What Is a DSCR Loan in Florida?
A DSCR loan is a non-QM loan program for rental properties where qualification is based on the property's rental income, not the borrower's personal income. With DSCR loans, Ridge Street measures whether the rent covers the property's principal, interest, taxes, insurance and association fees (PITIA). DSCR loans are one of the most popular loan programs for Florida real estate investors because they are highly scalable and work well with popular investing strategies.
Florida offers opportunities for both long-term and short-term rental investments, and DSCR loans can finance either strategy. Since qualification depends on the property's rental income instead of the borrower's personal debt-to-income (DTI) ratio, investors can purchase or refinance multiple properties without the conventional financed-property limit. This flexibility makes DSCR financing particularly attractive for investors building larger portfolios across Florida.
However, Florida's insurance costs can affect DSCR qualification. High windstorm and flood insurance premiums increase PITIA and may push the DSCR below 1.0. Coastal and flood-zone properties may also require an elevation certificate for insurance quotes.
Condo financing presents additional challenges. Florida's milestone inspection and structural reserve requirements, along with pending special assessments, can affect eligibility. Depending on the building's condition and finances, investors may need a non-warrantable condo loan or a specialized DSCR program.
How Florida Investors Use DSCR Loans
- Purchasing long-term rentals, including single-family homes, condos, and small multifamily properties in Miami, Fort Lauderdale, Tampa, Orlando, Jacksonville, and suburban markets across Florida.
- Financing short-term rentals through Airbnb financing, with DSCR loans for Airbnb allowing qualification based on projected rental income, even without booking history.
- Refinancing BRRRR projects, where investors purchase, renovate, rent, and then cash out refinance their properties when executing the BRRRR investing strategy.
- Portfolio expansion for investors scaling across multiple properties without personal debt-to-income (DTI) constraints.
When Not to Use a Florida DSCR Loan
While this loan program is well-suited for financing income-producing rental properties, there are DSCR loan pros and cons to consider, as these loans are not suitable for:
- Owner-occupied properties, including primary residences and second homes for personal use
- Properties with insufficient rental income to cover debt service
- Properties purchased for quick resale that require short-term bridge financing (Bridge-to-Sell)
- Distressed or value-add properties that are not yet rent-ready or stabilized with rental income
Benefits of Florida DSCR Loans vs. Conventional Financing
The key advantages of DSCR loans compared to conventional financing options are:
- No personal income verification
- No tax returns or W-2s
- Scalable for growing portfolios
- Less documentation than conventional loans
- Ability to close a DSCR loan in an LLC
- DSCR loans do not report to personal credit
DSCR LOAN PRODUCTS
Florida DSCR Loans Rates & Terms
Long Term Rental
DSCR Loans Florida
Origination fee
from 0%
LTV, purchases
up to 80%
LTV, cash-out refinances
up to 75%
Loan size
$55,000 to $2,000,000
Closing
as little as 21 days
Short Term Rental
DSCR Loans Florida
Origination fee
from 0%
LTV, purchases
up to 80%
LTV, cash-out refinances
up to 75%
Loan size
$125,000 to $2,000,000
Closing
as little as 21 days
5-10 Unit Multifamily
DSCR Loans Florida
Origination fee
from 1.0%
LTV, purchases
up to 75%
LTV, cash-out refinances
up to 70%
Loan size
$350,000 to $2,500,000
Closing
as little as 30 days


DSCR LOAN CHECKLIST
DSCR Loan Florida Requirements
A complete checklist of the borrower requirements, property requirements and documents needed for a DSCR loan in Florida with Ridge Street.
Borrower Requirements
- Credit score: 660+
- No mortgage lates in the last 24 months
- Liquidity: closing costs plus 6 months PITIA
- First-time investors allowed
- Personal borrower or LLC
- US citizen or permanent resident
Property Requirements
- Property type: 1-4 unit residential or 5-10 unit residential
- DSCR of 1.0 or higher
- Property must be rent-ready
- Vacant properties permitted for both purchases and refinances
Document Checklist
- Photo ID
- Bank statement
- Entity documents (articles of formation, EIN, operating agreement) if closing in an LLC
- Appraisal, ordered by Ridge Street
- Completed loan application
How To Calculate DSCR For Florida Rental Properties
The Debt Service Coverage Ratio (DSCR) is calculated by dividing the monthly rental income of the property by the total debt service obligation.
DSCR = Rent ÷ PITIA
Where PITIA includes:
- Principal
- Interest
- Taxes
- Insurance
- HOA (if applicable)
The basis of a DSCR loan in Florida is that the rent collected from leasing the property must be greater than the total cost to own and operate it.
A DSCR of 1.0 or higher means the rental income covers all expenses and the property is considered to be cash-flowing.
Use our DSCR Loan Calculator to estimate your property's DSCR and determine whether the property qualifies for a DSCR loan.
Quick & simple
Florida DSCR Loan Process
Our DSCR Loan origination process includes 5 steps with reliable funding in 21-25 days.

Apply Or Get Pre-Approved Online
~ 2 minutes
Fill out a 2 Min Quick App with info about your project. We need some preliminary information so that we can accurately evaluate your deal and provide a quote.
If you’re looking to be pre-approved so that you can find your next deal or you’d like to get more info from one of our team members, select an option below.

Receive Your Term Sheet
~ 2 hours
Once we have your completed application, we’ll email you the Term Sheet and give you a call to provide confirmation.

Submit Docs & Order Appraisal
~ 1–7 days
Once you’ve accepted the Loan Terms, we’ll collect your remaining documents and order an appraisal. We have a low document program with no income statement documentation. See our full dscr loan requirements document checklist.

Underwriting And Final Approval
~ 2–5 days
Once you've submitted your documents and we've received the completed appraisal, the loan will enter the underwriting process. Underwriting is simply an internal review of your borrower documents and title documents before the loan is cleared to close.

Closing
~ 2 days
Once the loan is cleared to close, the title company will schedule a time for closing. Loans typically close within 48 hours of final approval.
Types of DSCR Financing Available in Florida
DSCR Purchase Loans in
Florida
- An investor has found a rental and has the down payment, but can't qualify based on tax returns.
- Purchasing a rental property with ownership held through an LLC.
- Loan terms depend on DSCR, credit score and LTV.
DSCR loan guide
Rate-and-Term Refinance in Florida
- A rental property owner wants better financing terms on an existing mortgage.
- Replaces existing debt with a long-term mortgage.
- May reduce monthly payments or provide more predictable financing terms.
Refinance guide
DSCR Cash-Out Refinance in Florida
- A rental property owner has built equity and wants to fund another investment.
- Accesses equity for the next purchase, property improvements or reserves.
- Allows up to 75% LTV, subject to appraised value and existing loan payoff.
DSCR cash-out guide
DSCR Loans For Airbnb Rentals in Florida
- A buyer wants to finance a vacation rental with seasonal income and no long-term lease.
- Qualifies based on projected or actual short-term rental income.
- Must meet property eligibility, local STR regulations, and insurance requirements.
DSCR for Airbnb Guide
Florida Market insights
Best Florida Rental Markets for DSCR Loan Investors
Florida remains one of the most active states for rental property investors, with sustained population growth, a tourism economy that keeps short-term rental demand steady, and a diversified employment base across finance, healthcare, logistics, and aerospace. The state's no-income-tax structure continues to attract both retirees and working-age households from higher-cost regions, feeding reliable long-term rental demand in most major metros. Florida consistently ranks among the best states to buy rental property, and the five markets below represent its highest-volume investor destinations.
DSCR Loans in Orlando
Orlando remains one of Florida's most active rental markets, driven by its tourism economy, sustained population growth, and a tenant base that spans hospitality workers, healthcare professionals, and a growing technology sector concentrated around the University of Central Florida and the Lake Nona Medical City corridor. Zillow reports an average rent of around $1,900 per month across all property types in mid-2026, with single-family rental demand concentrated in suburbs like Winter Garden, Lake Nona, and Lake Mary.
Disney World, Universal, and the newly expanded Epic Universe keep short-term rental demand strong, though whole-home STRs within Orlando city limits are restricted to home-sharing, so most vacation-rental investors look to Osceola and Polk counties instead.
With a resilient tenant base and multiple demand drivers, investors can use DSCR loans to build long-term rental portfolios or add vacation-rental inventory in the right submarkets.
DSCR Loans In Tampa
Tampa-St. Petersburg has become one of the most sought-after rental markets on Florida's Gulf Coast, drawing retirees, remote workers, and corporate relocations from higher-cost Northeast and Midwest metros. The region's economy is anchored by finance (Raymond James, Citigroup), healthcare (Moffitt Cancer Center, Tampa General), and defense (MacDill Air Force Base and the SOCOM community), giving the rental base unusual depth.
Zillow puts the average rent near $2,000 per month in 2026, with single-family rental demand strongest in Wesley Chapel, Riverview, and surrounding Pasco County, where new-construction inventory and family-sized homes are easier to find. The Tampa Bay region is projected to add roughly 400,000 residents through 2030.
With steady migration-driven demand and still-reasonable pricing in the outer submarkets, investors can use DSCR loans to build portfolios in a market set for its next rent cycle.
DSCR Loans In Miami
Miami has one of the most international rental markets in the United States, anchored by a tenant base that spans finance and tech workers from New York and California migration, Latin American capital, international professionals, and a steady flow of tourists and seasonal residents. The city's role as the gateway to Latin America, combined with the Brickell financial district, the Wynwood and Design District tech and creative cluster, and major healthcare employers, keeps rental demand consistent across the price spectrum.
Zillow's average rent sits near $3,200 per month in 2026, among the highest in the Southeast. Miami Beach and parts of Miami-Dade restrict short-term rentals in residential zones, so submarket selection matters for STR investors.
With premium rents and a deep international tenant base, investors can use DSCR loans to acquire strong cash-flowing properties in a globally recognized market.
DSCR Loans in Jacksonville
Jacksonville offers investors a combination of affordability, steady population growth, and an expanding job market anchored by healthcare (Mayo Clinic, Baptist Health), financial services (Fidelity, Bank of America operations), and the Jacksonville Port Authority, one of the busiest logistics hubs on the Southeast coast.
Zillow reports an average rent in the $1,500 to $1,700 range in 2026, among the most accessible for a major Florida metro. Single-family rental demand is concentrated in San Marco, Avondale, Riverside, and Nocatee, with newer build-to-rent inventory expanding across the Southside and St. Johns County. The city has ranked among the top U.S. metros for net migration for three years running.
With accessible entry prices and a market still early in its rent-growth cycle, investors can use DSCR loans to build long-term rental positions ahead of further appreciation.
DSCR Loans In Fort Lauderdale
Fort Lauderdale has emerged as one of South Florida's most consistent rental markets, drawing professionals who work along the Las Olas financial corridor, the Cypress Creek office submarket, and the growing fintech and marine industries. The city combines waterfront lifestyle demand with steady visitor traffic through Port Everglades, one of the three busiest cruise ports in the world, and Fort Lauderdale-Hollywood International Airport.
Zillow's average rent sits near $2,750 per month in 2026, and entry prices typically run 15% to 25% below comparable Miami properties, giving investors South Florida exposure without the price compression of the Miami market. Broward County allows short-term rentals under moderate local rules, unlike neighboring Miami Beach.
With consistent demand from a diversified tenant base, investors can use DSCR loans to add waterfront-market exposure without the acquisition premium of Miami proper.
What Investors Say
From real estate investors who closed Hard Money and DSCR Loans with Ridge Street Capital across 36 states.
Florida DSCR Loan FAQ
Can I get a Florida DSCR loan if I live in another state?
Yes. A DSCR loan qualifies on the property's rental income, so where you live does not affect approval. The requirements are the same for out-of-state investors as for Florida residents.
Do HOA fees and rental restrictions affect DSCR loan approval in Florida?
Yes, in two ways. HOA dues are part of the monthly payment used in the DSCR calculation, so high dues lower the ratio. On a rental that brings in $2,500 per month, $400 in dues takes the DSCR from 1.25 to 1.04.
Rental restrictions matter too. Florida associations can set minimum lease terms, cap the number of leases per year or require tenant approval. Read the declaration before closing, because recorded restrictions apply to every new buyer.
Can I get a DSCR loan on a Florida condo?
Yes, condos are eligible. With a condo, the lender reviews the building as well as the unit: the association's budget and reserves, owner delinquencies and any litigation.
Florida adds one more step. Buildings of three or more stories must complete a milestone inspection at 30 years of age and keep a structural integrity reserve study. A pending special assessment or underfunded reserves can limit financing, so ask the association for these documents before signing a contract.
Do I need flood or windstorm insurance for a DSCR loan in Florida?
Wind coverage is required on every Florida DSCR loan. If the property insurance policy excludes wind, a separate windstorm policy is needed. Flood insurance is required when the property sits in a FEMA Special Flood Hazard Area.
Both premiums count toward the monthly payment in the DSCR calculation, so get an insurance quote before making an offer.
How do Florida property taxes affect my DSCR?
Property taxes are part of the monthly payment used in the DSCR calculation, so a higher tax bill lowers the ratio.
In Florida, the seller's tax bill often understates what the buyer will pay. The assessed value of a rental property can rise by no more than 10% a year, but that cap ends when the property sells, and the county reassesses it at market value the following January 1. Estimate the DSCR with taxes based on your purchase price, not the seller's last bill.
Can I qualify for a Florida DSCR loan using Airbnb income?
Yes. Short-term rentals in Florida can qualify on projected income, so the property does not need booking history. Ridge Street uses AirDNA data to project the cash flow for the DSCR calculation.
The projection only counts where short-term rentals are legal. Florida law stops cities from banning vacation rentals outright, but local rules adopted before June 2011 still stand. Miami Beach, for example, prohibits them in most residential zones, so check the city and county rules before making an offer.
What closing costs should I expect on a DSCR loan in Florida?
Closing costs on a Florida DSCR loan include the usual lender and title fees plus two state taxes on the mortgage. On a $300,000 loan, the two taxes come to $1,650.
- Documentary stamp tax: $0.35 per $100 of the loan amount
- Intangible tax: 0.2% of the loan amount
- Appraisal
- Title search and title insurance
- Title agent and recording fees
- First-year property insurance premium
- Origination fee, from 0%
Does my LLC have to be registered in Florida to close a DSCR loan?
Yes. The LLC on title must be registered with the Florida Division of Corporations and in good standing at closing. An LLC formed in another state can still be used, but it has to register in Florida as a foreign entity first.
Does the property have to be rented to refinance with a DSCR loan in Florida?
No. A vacant property can be refinanced as long as it is rent-ready. Without a lease in place, the DSCR is calculated on the market rent from the appraisal. This suits investors who refinance a hard money loan right after a renovation, before a tenant moves in.
Do DSCR loans in Florida have a prepayment penalty?
Most do, but you choose the term. Ridge Street offers 5-year, 3-year and 1-year prepayment penalties, plus an option with no penalty. The longer the penalty period, the lower the rate.
The penalty applies only if you sell or refinance during that period. Florida does not restrict prepayment penalties on investment property loans, so all four options are available here.
Can I get a DSCR loan in Florida with no money down?
No. DSCR lenders do not offer 100% financing, and the minimum down payment on a Florida DSCR loan is 20% of the purchase price. On a $300,000 rental, that is $60,000.
Investors who already own a rental often fund the down payment with a cash-out refinance on that property or with 1031 exchange proceeds.
What affects my DSCR loan rate in Florida?
Five factors set DSCR loan rates in Florida:
- DSCR: a higher ratio earns better pricing
- LTV: a larger down payment lowers the rate
- Credit score: a higher score earns a lower rate
- Property type: single-family homes price lowest, then 2-4 units
- Prepayment penalty: a longer penalty period lowers the rate
In Florida, a high insurance premium or a property tax bill reassessed after the sale lowers the DSCR, which can raise the rate.
What is the minimum DSCR required in Florida?
Yes, as long as the LLC is registered in the State of Florida, a DSCR loan can be funded in the name of your LLC. Check out our Complete Guide To DSCR Loans for more info.
Can I close a DSCR Loan in an LLC?
Yes, as long as the LLC is registered in the State of Florida, a DSCR loan can be funded in the name of your LLC. Check out our Complete Guide To DSCR Loans for more info.
Additional DSCR Loan Resources
Category
October 29, 2026
A complete guide to Airbnb investment analysis: the metrics that decide a short-term rental deal, how to use AirDNA data
Category
October 13, 2026
Many non-warrantable condos still qualify for DSCR financing. This guide explains which conditions only affect conventional loans and which ones create broader lending risk.
Category
October 21, 2026
An experienced out-of-state investor purchased a single-family rental in Seminole, Florida with 20% down and a 1.42 DSCR. The deal closed in under 30 days.
Beginner & Experienced Investors
Ready to get a Florida DSCR loan?
Whether you have a property under contract, you're looking to be pre-approved so you can find your next deal, or you'd like to speak with an expert, Ridge Street is a leading DSCR lender in Florida and can help.