DSCR Cash-Out Refinance: How It Works and How Much You Can Access
Access rental property equity without personal income verification. Learn what lenders require, how LTV affect cash-out amounts, and how seasoning works.
nmin readReleased on:October 24, 2025Last updated on:November 2, 2026
Overview:
- Cash-out and Rate-and-term refinances serve different purposes. A rate-and-term refinance keeps the loan balance largely unchanged while adjusting the interest rate or repayment term. A cash-out refinance increases the loan balance to release equity, typically at a higher interest rate due to the additional risk.
- DSCR cash-out refinancing generally allows up to 75% of the appraised value, with a minimum DSCR of 1.0 and better pricing at 1.20 or higher. Most lenders require 6 to 12 months of ownership, although investors refinancing a stabilized property out of hard money financing may qualify sooner.
- Cash-out refinancing increases the amount owed and can raise monthly payments, reducing cash flow. However, the proceeds are borrowed funds rather than taxable income, allowing investors to access equity without selling.
A DSCR cash-out refinance allows real estate investors to pull equity from an income-producing property without using personal income to qualify. The loan replaces the existing mortgage with a larger one, and the difference, the cash-out amount, is disbursed to the borrower at closing.
Equity sitting in a stabilized rental property does not generate a return unless it is deployed. Without refinancing, that equity remains locked in the asset unless the property is sold. A DSCR cash-out refinance converts that equity into liquid capital while allowing investors to keep the property in the portfolio and continue to generate income.
Investors commonly use the proceeds to acquire additional properties, fund value-add renovations, or pay down higher-cost debt.
This guide explains how a DSCR refinance works, the difference between cash-out and rate-and-term refinancing, the qualification requirements, and when refinancing makes sense versus when it does not, so investors can clearly evaluate when to use this strategy.
What Is a DSCR Cash-Out Refinance?
A DSCR cash-out refinance is a non-QM investment property loan for rental properties. The investor refinances an existing mortgage into a new, larger loan and receives the difference between the two balances as cash at closing. Approval is based on the property's rental income relative to the new loan payment, not the borrower's personal income, tax returns, or employment history.
Lenders calculate the DSCR ratio by dividing the property's monthly rental income by its monthly PITIA payment: principal, interest, taxes, insurance, and association dues, where applicable. A DSCR of 1.0 means the property's rental income fully covers the debt obligation.
DSCR Loan Refinance Options: Rate-and-Term vs. Cash-Out
DSCR refinance loans for investment properties generally fall into two categories: rate-and-term refinance and cash-out refinance. Each structure serves a different purpose depending on the investor’s objective.
What Rate-and-term Refinance Gives You
It replaces your existing mortgage with a new loan at a lower interest rate, a different loan term, or both. The new loan principal matches your current outstanding balance, meaning that no cash comes out.
The goal is to reduce your monthly payment, shorten the payoff timeline, or move from a short-term bridge loan into a long-term DSCR loan after a renovation is complete. Rate-and-term refinances carry lower rates than cash-out refinances because the lender's risk position doesn't change.
What Cash-out Refinance Gives You
A cash-out refinance increases the loan balance above what you currently owe. The new loan pays off the existing mortgage, and the difference between the new principal and the old payoff is released to you at closing. The trade-off is a higher new loan balance, a higher monthly payment, and tighter LTV requirements.
- If the goal is to improve the loan terms on a property you plan to hold long term, a rate-and-term refinance is typically the right structure.
- If the objective is to access equity and pull capital from the property, a cash-out refinance is the appropriate option.
How Much Can You Cash Out on a DSCR Refinance?
The maximum loan amount on a DSCR cash-out refinance is 75% of the current appraised value of the investment property. The cash-out amount is the new loan minus the payoff on the existing loan, closing costs, and prepaid items.
Here is a real example of Ridge Street Capital's term sheet for a rental property that shows how this works in practice.
In this example, the new $412,000 loan paid off a $125,000 mortgage, and the investor received an estimated $275,537 after costs. Closing costs go beyond the lender fee. The lender cost was $1,995 for underwriting and legal, with 0% origination.
The investor also paid estimated title fees, the insurance premium, three months of tax and insurance escrow, and one month of prepaid interest. Together, these items came to about $11,463, or roughly 2.8% of the loan amount.
The property’s DSCR determines whether the full 75% is available. Here, $4,000 in monthly rent against a $3,251.05 total payment produces a 1.23 DSCR. That clears the 1.0 minimum and leaves $748.96 in monthly cash flow after the new payment.
If rent barely covered the payment, the lender could cap the loan below 75% to bring the ratio up to the required level, which would reduce the cash out.
These figures are estimates subject to final underwriting and approval. The appraisal, the payoff balance, and the final closing costs all move the number. This loan also carries a 60-month prepayment period, which investors should weigh if a sale or another refinance is likely within five years.
Investors can run their own numbers with Ridge Street’s DSCR refinance calculator.
How DSCR Cash-Out Refinance Works
The DSCR cash-out refinance process follows a straightforward sequence, from application to closing and funding. Unlike conventional refinancing, which requires collecting and verifying personal income documents, the DSCR loan process is faster because the file is built entirely on property-level documentation. Check our DSCR Loan vs Conventional Loan for a full comparison.
1. Initial review. The lender collects the rent roll, existing loan balance, and operating expenses to confirm the property qualifies and to estimate the maximum loan amount before ordering an appraisal.
2. Appraisal. An independent appraisal provides the current market value and confirms the market rent figure used to calculate DSCR. The appraised value drives the LTV ceiling and the cash-out amount.
3. Underwriting. The lender checks all the documents, verifies DSCR, LTV, credit score, and property eligibility. Underwriting typically completes within 7-10 days after the appraisal.
4. Loan terms set. Rate, amortization schedule, and prepayment structure are finalized based on the confirmed DSCR, credit profile, and appraised value.
5. Closing. At closing, the new loan pays off the existing mortgage, and the remaining equity proceeds are disbursed to the borrower.
DSCR Cash-Out Refinance Requirements
Minimum DSCR
Most DSCR lenders, including Ridge Street, require a minimum ratio of 1.0, meaning the property's rental income must at least equal the full debt service. A stronger DSCR of 1.20 or above supports better pricing and provides additional cushion if rents decline or property expenses increase.
Maximum LTV
Cash-out refinances are capped at 75% LTV, meaning the new loan cannot exceed 75% of the appraised value. The remaining 25% equity stays in the property as a buffer against value fluctuations.
Seasoning
Ridge Street Capital requires at least 6 months of property ownership to qualify for a DSCR cash-out refinance. This waiting period, known as seasoning, allows lenders to review the property's ownership history, rental income, and performance before approving the refinance. Requirements vary by lender and loan program, so investors should confirm the seasoning period when planning their refinancing strategy.
However, an exception applies to certain renovation and BRRRR deals. If an investor uses a hard money loan to purchase and renovate a property, they may qualify for a cash-out refinance once the renovation is complete and the property is stabilized, without waiting through the standard six-month seasoning period.
Rate-and-term refinancing follows different rules. Ridge Street has no seasoning requirement for DSCR rate-and-term refinances, allowing investors to change their interest rate, loan term, or both without a mandatory waiting period, provided the property meets the lender's qualification requirements.
Credit Score
The minimum credit score for a DSCR cash-out refinance is 660 at Ridge Street Capital. Every DSCR loan carries a personal guarantee from the borrower, which means the lender evaluates credit independently of the property's income. The credit score measures personal default risk. A higher score produces better pricing and stronger leverage terms on the same deal.
Property Types
DSCR cash-out refinances are available on:
- Single-family rentals
- 2-4 unit properties
- Condos and townhomes
- Short-term rentals
Because DSCR loans are business-purpose mortgages, owner-occupied properties are not eligible, and the property must be in rent-ready condition.
When a DSCR Refinance Makes Sense and When It Doesn't
A cash-out refinance works when the rental property’s fundamentals support the new loan structure and the investor has a clear plan for how the proceeds will be deployed. For a full breakdown of the advantages and tradeoffs of this financing structure, see the DSCR loan pros and cons guide.
DSCR Refinance makes sense when:
- The property has a meaningful DSCR cushion above 1.0 at the new loan amount.
Pulling equity to the point where the property barely covers its debt service leaves no margin for vacancy or repairs. A refinance with a DSCR of 1.15 or higher provides enough cushion to absorb rent declines or expense increases without forcing the investor to cover the gap out of pocket.
- The equity position is strong enough that 75% LTV still produces a meaningful loan.
If the property has limited appreciation since purchase, the cash-out amount may not justify the increased loan balance and closing costs.
- The proceeds have a clear deployment plan.
A cash-out refinance can help investors grow their portfolios faster when they put the released equity to productive use. This might mean funding a down payment on another investment property, renovating an existing rental to increase its value, or paying off higher-interest debt.
However, withdrawing equity without a clear investment plan increases the loan balance and interest costs without generating additional returns.
- The tax treatment of the proceeds is part of the strategy.
Cash-out refinance proceeds are borrowed funds, not taxable income, so accessing equity does not trigger a taxable event at closing. By contrast, selling an appreciated property may create a taxable capital gain.
Refinancing allows investors to access that equity without selling the property, making it an attractive option for funding another acquisition. This is one of the tax benefits of real estate investing that investors can consider when planning their financing strategy.
Consult a CPA to understand the tax implications of your specific situation.
- The existing loan is a hard money or bridge loan.
A DSCR cash-out refinance is a common exit strategy for investors who use short-term financing to purchase and renovate a property. Once renovations are complete and the property generates stable rental income, investors can use a DSCR loan to pay off the hard money loan and transition to long-term financing.
The additional cash-out proceeds allow investors to recover some or all of their renovation capital, completing the refinancing stage of the BRRRR loans strategy and freeing up funds for another investment.
DSCR Refinance doesn't make sense when:
- The DSCR at the new loan amount falls below 1.0 or barely clears it.
Most lenders will not approve a cash-out refinance with a marginal DSCR. Even if the loan qualifies, the property begins the new loan term with little room to absorb rent declines or expense increases.
- The property is within the first 6 months of ownership.
Most lenders require at least 6 months of ownership before allowing a cash-out refinance because a newly acquired property has not yet established documented rental performance.
- A sale is planned in the near term.
DSCR loans typically include prepayment penalties that decrease over the first three to five years. If an investor sells or refinances during this period, the penalty can reduce the proceeds they receive. Investors should consider their planned holding period and potential exit costs before closing.
- The cash-out amount is small relative to closing costs.
On a property with limited equity, the proceeds available at 75% LTV may not justify the transaction. If the accessible equity is $30,000 to $40,000, closing costs consume a significant share of that figure. In that situation, it may make more sense to leave the equity in the property and finance the next acquisition through a different structure.
DSCR Cash-Out Refinance Case Studies
The three case studies below illustrate how DSCR cash-out refinancing works across different property types and borrower situations: a stabilized multifamily property in New York, a leased single-family rental in Plano, Texas, and a single-family property in Oxford, Alabama, refinanced by borrowers. In each case, the loan qualified based on the property's rental income, without requiring personal income verification.
DSCR Cash-Out on a Stabilized Multifamily Property in New York
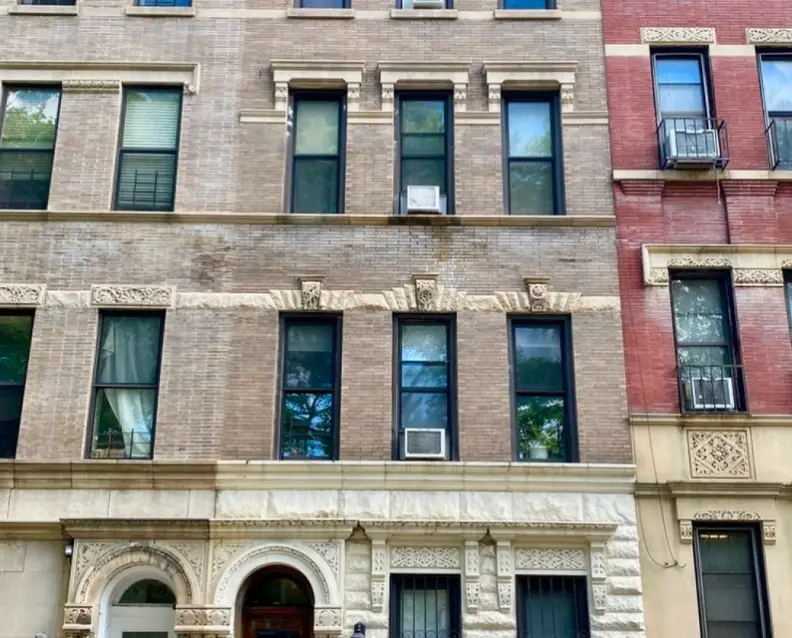
A recent Ridge Street Capital transaction involved a stabilized 5-unit multifamily property valued at $2.65 million in New York. The borrower had held the property for several years and wanted to pull equity out while also improving cash flow by moving into a lower-rate, long-term DSCR loan. Ridge Street structured a $1.55M loan at 7.375% on a 30-year amortization, replacing a higher-rate existing mortgage and delivering the cash-out proceeds the investor needed for their next acquisition.
The deal required navigating several structuring complexities. Read the full transaction details on how we saved our client $25,000 in the multifamily DSCR cash-out refinance case study.
Pulling Equity from a Leased Single-Family in Plano, TX
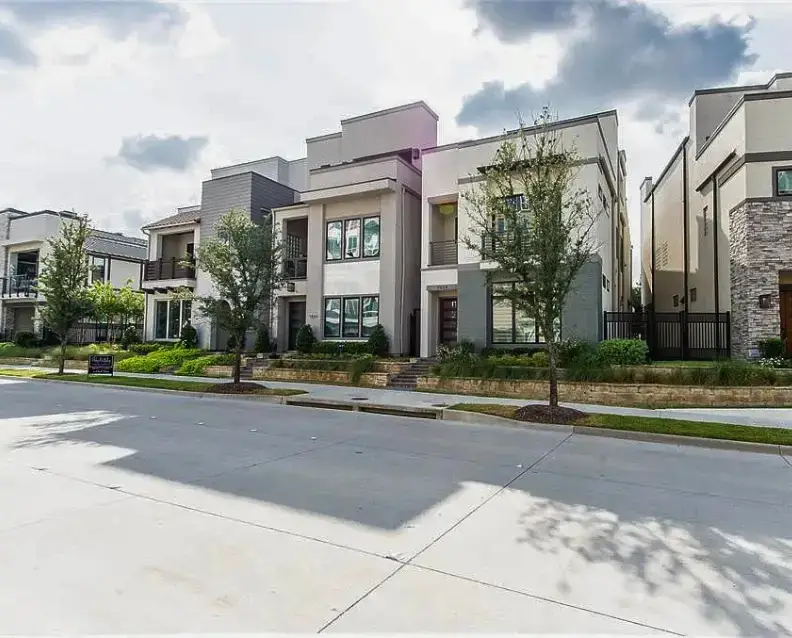
A borrower in Legacy West, Plano, Texas, owned a 2021-built single-family rental appraised at $1,219,000 and leased under a two-year lease. The goal was to access equity without selling, since a sale would have meant losing the tenant and paying transaction costs and potential tax exposure. Ridge Street Capital underwrote on the lease through its Texas DSCR program. The 63.17% LTV left more than $449,000 in equity in the property. Read the full Plano case study.
DSCR Cash-Out Refinance Example Deal in Oxford, Alabama

Four co-owners refinanced a tenant-occupied rental in Oxford, Alabama to fund improvements and a new down payment. Ridge Street Capital coordinated with title in advance and closed on schedule. Read the full Oxford case study.
Turn Equity into Opportunity with Ridge Street Capital
At Ridge Street Capital, we help investors structure DSCR refinances that support long-term portfolio growth. If you have equity in a rental property and want to understand what financing options are available, Ridge Street can run numbers with you and issue a term sheet within 2 business hours, with no cost or obligation.
Frequently Asked Questions
Can you refinance a DSCR loan?
Yes. DSCR loans can be refinanced into a new DSCR loan at a lower rate, a longer term, or a cash-out structure. The refinancing property must still meet the minimum DSCR ratio at the new loan amount. Most programs require 6 months of ownership before a cash-out refinance, though BRRRR deals with a hard money exit are generally exempt from that requirement. Rate-and-term refinances have no seasoning restriction.
How is a DSCR cash-out refinance different from a conventional cash-out refinance?
A conventional cash-out refinance qualifies you based on personal income. The lender reviews tax returns, W-2s, and calculates your debt-to-income (DTI) ratio, which includes the mortgage payments on every investment property you already own. Each new property increases your DTI, and most conventional programs cap eligibility at around 40%. Once that limit is reached, qualifying for another conventional loan becomes difficult, regardless of how well the properties perform.
A DSCR cash-out refinance qualifies based on the property’s rental income and whether that income covers the new loan payment. An investor with ten properties is qualified the same way as an investor with one property, as long as the subject property produces sufficient cash flow.
Can I do a DSCR cash-out refinance in an LLC?
Yes. DSCR loans are business-purpose loans and are commonly closed in the name of an LLC. The property still needs to meet DSCR and LTV requirements, and the LLC borrower must meet the minimum credit score requirement. If you're evaluating the LLC structure for asset protection or tax reasons, a DSCR loan is the right product for that.
Can I use the cash proceeds to buy another property?
Yes. There's no restriction on how you deploy the proceeds. Using cash-out equity to fund the down payment or closing costs on another acquisition is one of the most common reasons investors refinance. The new loan remains attached to the refinanced property, while the cash-out proceeds can be deployed however the investor chooses.
Will a cash-out refinance hurt my monthly cash flow?
It will reduce it. A higher loan balance means a higher monthly payment, and a higher monthly payment means less net cash flow per month. The key question is whether the reduced cash flow on the refinanced property is offset by the return generated from the capital being pulled out. Before closing, model both sides of the equation: the property’s cash flow under the new loan payment and the expected return on the deployed proceeds.
Can I qualify if my property has been recently renovated?
Yes. Some lenders offer no-seasoning cash-out options for recently renovated or value-added properties with documented increased market value and stabilized rent rolls. This allows investors to access equity sooner to fund the next phase of their real estate investment strategy.
Zach Cohen is the Managing Partner of Ridge Street Capital, a direct private lender providing hard money and DSCR loans to real estate investors across 36 states. Under his leadership, the firm has funded nearly $90 million in investment property loans. He regularly works with real estate investors on rental property acquisitions, refinances, and fix-and-flip projects across the country.
Fix and Flip Loans
Funding For Purchase + Rehab
- $50,000 up to $3,000,000
- Interest Rate 10.5%-11.5%
- Origination Fee From 1.5%
- Up to 90% of Purchase and 100% of Rehab

DSCR Loans For Long Term Rentals
Perfect for first-time investors or experienced investors scaling their rental portfolio.
- Up to $2,000,000
- Interest Rates from 6.0%
- Origination Fee From 0%
- Up to 80% of LTV

DSCR Loans For Short Term Rentals
Designed for investors pursuing higher rents with a short term rental strategy.
- Up to $2,000,000
- Interest Rates from 6.25%
- Origination Fee From 0%
- Up to 80% LTV
Ready to Get Started?