Short-Term Rental Loans: How to Finance an Airbnb or Vacation Rental
Financing an Airbnb or vacation rental? Learn how DSCR, conventional, and hard money loans work, what lenders require, and when each option makes sense.
nmin readReleased on:October 24, 2025Last updated on:October 29, 2026
Overview:
- Short-term rental loans are a category of financing, not a single product. DSCR loans fund rent-ready purchases and refinances, fix-and-flip loans fund acquisition and renovation before listing, and conventional or second-home loans serve borrowers who qualify on personal income.
- STR DSCR lenders qualify a property on projected nightly rental income rather than long-term market rent, using AirDNA or trailing revenue with a conservative adjustment.
- Ridge Street’s STR DSCR program requires a minimum 700 FICO, 20% down on a purchase, and six months of PITIA in post-closing reserves.
Short-term rental loans finance investment properties that generate income through Airbnb, VRBO, Booking.com and other booking platforms rather than traditional long-term leases. This difference in how rental income is generated also affects how lenders evaluate the property during underwriting.
For long-term rentals, income is relatively predictable. A 12-month lease establishes a fixed monthly rent, which lenders can use to evaluate the property's ability to cover mortgage payments.
Short-term rentals work differently. Their income depends on nightly rates, vacancy, and market demand, which can fluctuate throughout the year. Conventional mortgage programs generally rely on documented rental income and may not fully account for a property's projected short-term rental potential.
Specialized short-term rental loan programs address this challenge by allowing lenders to evaluate projected income from daily bookings, accounting for occupancy, and sasonaliy.
In this guide, we explain the financing options available to short-term rental investors, how lenders evaluate each loan type, and which programs are best suited to different investment strategies.
What Are Short-Term Rental Loans?
The term "short-term rental loan" refers to a category of financing options rather than a single loan product. Investors use different programs depending on their investment strategy and the property's condition.
These include DSCR loans for rent-ready properties, hard money and fix-and-flip loans for acquisitions and renovations, and conventional investment mortgages for borrowers who qualify based on personal income. Second-home loans may also be available when the property meets personal-use requirements.
The main difference is how lenders qualify borrowers. Short-term rental loan programs evaluate projected or actual income from Airbnb, VRBO, and other vacation rentals to determine whether the property can cover its monthly mortgage payments, which include principal, interest, taxes, insurance, and association dues.
Since these loans do not rely on W-2 income or personal debt-to-income (DTI) calculations, investors can finance additional properties and grow their short-term rental portfolios without the same personal income constraints as conventional financing.
Short-Term Rental Loan Types
Short-term rental loans fall into three main categories. The table below provides a quick comparison, followed by a detailed explanation of each loan type.
DSCR Loans for Short-Term Rentals
DSCR loans are one of the most common financing options for short-term rental investors. Lenders qualify borrowers based on the property's projected or actual rental cash flow. Personal W-2 income or tax returns are not taken into consideration.
To estimate rental income, lenders use comparable market data or AirDNA projections. This is especially important for properties with no operating history.
All else being equal, the same property can generate more profit as a short-term rental than under a long-term lease. When a lender uses that higher income figure, the borrower may qualify for a larger loan amount, meaning less money out of pocket.
We've seen many cases where a vacation property falls below the minimum DSCR requirement when lenders use long-term market rent, but qualifies when they apply numbers from projected short-term rental income instead.
With this approach, investors may qualify for up to 80% LTV on STR purchases and 75% LTV on STR cash-out refinances.
DSCR lenders also don’t limit the number of properties a borrower can finance. Finally, investors can hold properties in an LLC. At Ridge Street Capital, these loans are typically closed within 21 to 25 days.
Ridge Street has a separate guide specifically for DSCR loans for Airbnb, which covers the full income evaluation methods, requirements, and common denial reasons.
Conventional / Second Home Investment Loans
Conventional investment loans follow Fannie Mae and Freddie Mac guidelines and generally offer the lowest investment property mortgage rates, often 0.25 to 0.5 percentage points below comparable DSCR loans for borrowers with similar credit profiles.
It’s important to note that conventional lenders qualify borrowers based on W-2 income, personal tax returns, and debt-to-income (DTI) ratios.
The DTI measures how much of a borrower's gross monthly income goes toward debt payments, including the new mortgage. Lenders often apply a ratio between 35% and 45%.
For short-term rental properties, there is an additional challenge. Conventional lenders often require 12 to 24 months of documented rental history before counting short-term rental income to determine how much a borrower can qualify for.
If a property has no history, lenders rely on long-term market rent instead, which is often lower than the property's actual or projected short-term rental revenue.
Second-home financing typically offers lower interest rates and down payments of 10% to 15%, making it more affordable than conventional investment property loans. However, borrowers must meet stricter eligibility and occupancy requirements.
Fannie Mae requires borrowers to occupy the property for part of each year, maintain exclusive control over its use, and ensure it is suitable for year-round occupancy. A property operated exclusively as a short-term rental generally does not meet these requirements. Therefore, second-home financing is primarily suited to properties that combine personal use with limited rental activity.
Location also matters. Although Fannie Mae does not specify a minimum distance from the borrower's primary residence, some lenders require second homes to be at least 50 to 100 miles away. Vacation and resort markets can be an exception to this rule.
Finally, these programs generally require borrowers to hold the property in their personal names. Not through an LLC.
Our second home vs. investment property guide explains these distinctions and the financing requirements in more detail.
As a result, conventional financing is often better suited to short-term rental investors with strong W-2 income, low DTI ratios, credit scores above 720, and properties held in their personal names.
For a more detailed comparison, see our DSCR vs. Conventional Loan guide.
Fix-and-Flip Loans for Short-Term Rental Rehabs
Properties that require significant renovation before operating as short-term rentals generally do not qualify for DSCR or conventional investment loans at purchase. These programs require properties to be habitable and rent-ready at closing. If the appraiser identifies major condition issues, the loan is denied.
In these cases, investors typically use a two-step financing strategy.
A fix-and-flip loan funds the acquisition and renovation on short-term, interest-only terms: 6 to 18 months, and rates in the 10% to 13% range. Once renovations are complete and the property is ready to generate rental income, the investor refinances into a long-term mortgage based on the property's improved value.
This is the short-term rental version of the BRRRR strategy, sometimes called AirbnBRRRR.
Which Short-Term Rental Loan Fits Your Situation?
Three main factors determine which short-term rental financing options are available: the property's condition and whether it is ready to rent, the investor's ability to qualify based on personal income, and the number of properties they already own.
The scenarios below show how these factors influence loan selection.
Acquiring a New STR Property With No Rental History
Investors can finance a new short-term rental property without an existing rental history through a DSCR loan. Instead of relying on past bookings, lenders estimate the property's potential income using AirDNA projections or comparable market data.
This makes DSCR financing one of the most practical options for new Airbnb purchases.
Refinancing an Existing Short-Term Rental to Access Equity
A DSCR cash-out refinance allows investors to access equity in an existing Airbnb property without selling it. Lenders typically allow up to 75% of the appraised value, provided the rental income supports the new mortgage payment and the borrower meets other qualification requirements.
Our Santa Rosa Beach cash-out refinance case study illustrates this approach. Ridge Street Capital helped the investor access $1,385,700 in equity through a cash-out refinance, closing the loan in just 22 days.
Acquiring a Distressed Property to Renovate and Convert Into an STR
For properties that need major repairs before they can operate as short-term rentals, investors generally start with a hard money or rehab loan. This allows them to purchase and improve the property, then transition to long-term DSCR financing once it is ready to rent.
Buying a Vacation Rental With Some Personal Use
For investors who plan to use a vacation property themselves while renting it out part of the year, second-home financing may be an option. The key consideration is how the property will be used.
If personal use is the primary purpose and rental activity is secondary, a second-home mortgage is a fit here. If the property is intended primarily as an STR investment, investors should consider an investment property loan and confirm with a lender whether personal use is allowed.
Scaling a Portfolio of Two or More Short-Term Rentals
DSCR financing allows investors to expand their portfolios without relying on personal debt-to-income calculations. Lenders evaluate each property's rental income, and most programs do not impose a fixed limit on the number of properties a borrower can finance.
For more details, see our guide on how to buy multiple rental properties.
Vacation Rental Loans vs. Short-Term Rental Loans: How Lenders Classify the Property
Vacation rental loans and short-term rental loans are often used interchangeably. However, the financing options available depend on how the lender classifies the property. This distinction affects loan eligibility, down payment requirements, and qualification criteria.
The key factor is how the borrower intends to use the property, rather than the property type or location. In practice, there are three common scenarios:
- Investment property.
The investor purchases the property primarily to generate rental income rather than for personal use. Depending on the loan program, personal occupancy may be restricted or prohibited entirely.
These properties can qualify for STR DSCR loans or conventional investment mortgages.
- Second home.
The borrower occupies the property for part of each year, maintains exclusive control over its use, and is not subject to a rental management agreement that restricts personal access.
Fannie Mae and Freddie Mac do not specify a minimum number of occupancy days, although individual lenders may impose additional requirements, such as distance from the primary residence.
Conventional second-home financing is available when these conditions are met, but lenders generally cannot use projected short-term rental income for qualification.
- Investment property with limited personal use.
Some investors want to operate a short-term rental as a business while occasionally staying at the property themselves.
This situation requires additional consideration. DSCR loans are business-purpose financing, and lenders generally require the property to be used for investment rather than personal occupancy.
Some loan programs prohibit all personal use. Therefore, investors should not assume that occasional stays are permitted simply because the property primarily generates rental income. Any intended personal use must be disclosed and confirmed with the lender in writing before closing.
Misrepresenting the property's intended occupancy can violate the loan agreement and lead to serious legal consequences.
For most investors purchasing a vacation rental primarily to operate as an Airbnb or VRBO, the property is classified as an investment property.
In these cases, a specialized STR DSCR loan is often the more practical financing option, particularly when qualification relies on projected rental income.
On the other hand, borrowers planning to spend extended periods at the property should consider conventional second-home financing. The trade-off is that they must qualify based on personal income and cannot generally rely on projected short-term rental revenue.
Down Payment and Reserve Requirements for STR Loans
Down payment, reserves, and closing costs vary by loan type.
In addition, closing costs typically range from 2% to 5% of the loan amount, covering lender fees, appraisal, title services, prepaid insurance, and tax escrows.
For example, on a DSCR purchase with 20% down, the total cash needed at closing may reach 25% to 30% of the purchase price after accounting for these expenses. Investors must also demonstrate sufficient cash reserves, although those funds remain in their own accounts after closing.
Common Mistakes When Choosing a Short-Term Rental Loan
Several common mistakes can delay short-term rental financing, reduce the approved loan amount, or cause lenders to decline a deal. Here are eight to avoid before applying.
1. Getting a Generic Pre-Approval Without Reviewing the Property
Many lenders offer DSCR loans as an additional product, but not all have experience underwriting short-term rentals.
As a result, investors may receive a generic pre-approval based on their credit score and available funds, without a detailed review of the property. The borrower may meet the basic requirements but encounter problems during the underwriting phase.
An experienced STR lender should review projected rental income, estimated DSCR, occupancy assumptions, and local market performance before the investor goes under contract.
2. Not Confirming Local Short-Term Rental Regulations
Before making an offer, investors should confirm that short-term rentals are permitted at the property's address.
Many municipalities restrict nightly rentals, require permits or registration, or limit the number of available STR licenses. Even if a property meets the lender's financial requirements, local restrictions may prevent the lender from using projected STR income or cause the loan to be declined.
3. Choosing a Lender Without Non-QM Experience
Some lenders advertise short-term rental financing but still use conventional mortgage underwriting processes. They may request W-2s, tax returns, and personal DTI calculations or require the property to be held in the borrower's personal name.
This becomes a problem when investors need to qualify using projected rental income or purchase rental property through an LLC.
Short-term rental DSCR loans fall within the non-QM lending market, where lenders offer different programs and eligibility requirements. However, not every non-QM lender specializes in STR financing.
Look for a lender or broker with experience in STR DSCR loans. Ask which income projections they accept and how they evaluate similar transactions.
Our Best Airbnb lenders guide compares lenders and their financing options.
4. Underestimating Closing Costs for Short-Term Rental Mortgage
A common mistake among first-time investors is assuming that having enough for the down payment means they are ready to close.
In addition to the down payment, borrowers must account for lender fees, appraisal, title and escrow charges, prepaid insurance, property taxes, and initial escrow deposits.
Lenders may also require liquid reserves after closing. These funds remain in the borrower's account, but they cannot be used toward the down payment or closing expenses.
Depending on the transaction, investors should plan for an additional 5% to 10% of the purchase price in closing expenses and available liquidity, then confirm the actual requirements with their lender.
5. Getting “Over-the-Phone Rate” Instead of a Written Term Sheet
A verbal rate quote may assume excellent credit, a strong DSCR, lower leverage, or discount points that the borrower has not considered.
Before choosing a lender, request a written term sheet showing the interest rate, origination fees, discount points, loan term, prepayment penalty, estimated cash to close, and required reserves.
The lender should also explain which assumptions could change the final terms during underwriting.
Instead of relying on advertised or preliminary rates, comparing written term sheets gives investors a clearer picture of the actual financing costs.
6. Relying Too Heavily on AirDNA Projections
AirDNA is widely used to estimate short-term rental income, but lenders do not necessarily accept its headline revenue projection at face value.
Many STR lenders, like Ridge Street, apply conservative adjustments, often using 80% of projected revenue to account for property management, platform fees, and market volatility.
It also helps to prepare an independent rental property pro forma using conservative revenue and expense assumptions.
7. Underestimating the Cost of Operating a Short-Term Rental
Lenders typically calculate DSCR using gross rental income divided by PITIA: principal, interest, taxes, insurance, and association dues.
However, this calculation does not include many expenses associated with operating a short-term rental. A property can meet the lender's minimum DSCR requirement and still generate negative cash flow after operating costs.
Three expense categories often surprise first-time Airbnb investors:
- Property management: Typically 15% to 25% of gross revenue for short-term rentals, compared with approximately 8% to 10% for long-term rentals.
- Furnishing and setup: Costs can range from around $10,000 for a small condo to $50,000 or more for a larger luxury vacation rental.
- Ongoing operating expenses: Utilities, Wi-Fi, cleaning, supplies, landscaping, pool maintenance, and other recurring costs.
These expenses may not appear in the lender's DSCR calculation, but they directly affect the investor's returns.
Before committing to a property, prepare a separate operating budget that accounts for all expected costs. Our Airbnb investment analysis guide explains how to estimate revenue, expenses, and net cash flow.
8. Not Keeping Enough Reserves for Seasonal Income Changes
Short-term rental income is rarely consistent throughout the year. Even when lenders qualify a property using annualized revenue projections, actual monthly income can fluctuate significantly.
Seasonality, weather, tourism demand, and changes in nightly rates can all affect bookings.
For this reason, investors should consider maintaining cash reserves beyond the lender's minimum requirement. Ridge Street Capital, for example, requires six months of PITIA in liquid reserves for its STR DSCR program.
Additional savings can help cover mortgage payments and operating expenses during slower months, unexpected repairs, or temporary declines in occupancy.
This is especially important for investors purchasing their first STR investment property who have not yet experienced a full seasonal cycle. Understanding these risks is an important part of evaluating whether a rental property is a good investment.
Funded Short-Term Rental Loans
Two recent Ridge Street Capital case studies illustrate how short-term rental financing works in practice. Both loans closed in 2026 on residential properties. In each case, the Ridge Street qualified the property using short-term rental income.
Saint George Island, FL. Beach condo qualified on AirDNA projections

Saint George Island is a barrier island off the Florida Panhandle with consistent vacation rental demand driven by beach tourism and limited inventory. A first-time investor from out of state acquired a 3-bedroom, 2-bathroom condo as a short-term rental, financed under Ridge Street's 30-year fixed STR DSCR program.
Long-term market rent of $2,648 per month would not have supported debt service. The file closed on the AirDNA short-term rental projection instead. Find more details about the St. George Island case study.
Cheyenne, WY. Dual-income underwriting
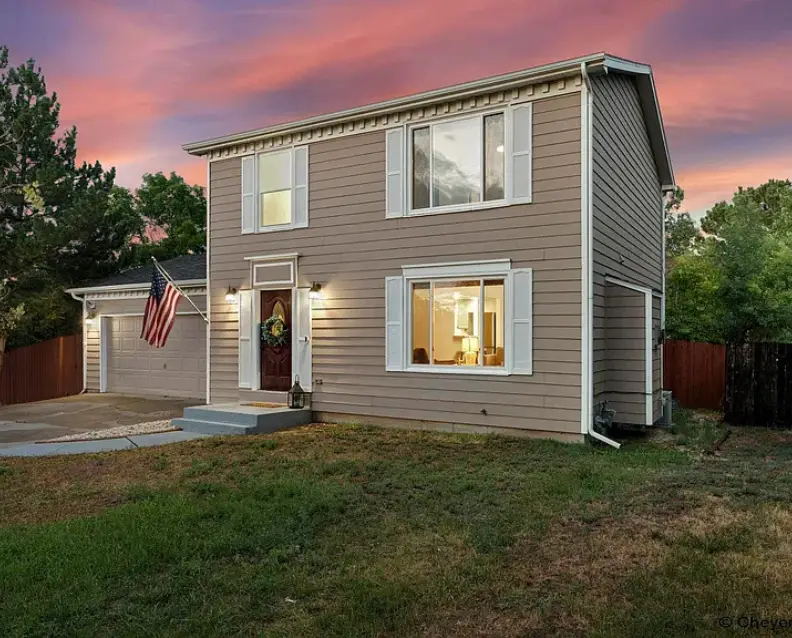
The property was a 3-bedroom, 4-bathroom single-family home in Cheyenne, Wyoming, purchased at $435,000 against a $445,000 appraisal, held through an LLC, and planned for STR operation.
The file was underwritten against both short-term and long-term rental income. Long-term comps alone produced a DSCR above 1.30, which cleared the floor without needing the AirDNA projection to carry the deal.
Dual-income underwriting is often the fastest route to a clean approval in markets that support both strategies. Read more info on the Cheyenne case study.
Finance Your Short-Term Rental with Ridge Street Capital
Ridge Street Capital finances short-term rentals across 36 states. Our Airbnb Financing programs qualify the property on projected or trailing nightly income with no personal income verification, no W-2s, and no tax returns. You can use our DSCR loan calculator to run your numbers.
Ridge Street originates both DSCR rental loans for the purchase and refinance of Airbnb and VRBO properties, and fix-and-flip loans for acquisitions that need renovation before they can be listed.
To get started, investors submit property details through our Quick Application. A loan officer reviews the deal, reconciles the STR income against AirDNA or trailing revenue, and issues a term sheet.
Frequently Asked Questions
Do you finance rural STR properties?
Yes. Properties near vacation destinations, lakes, mountains, national parks, and other tourism-driven areas are commonly eligible. Extremely remote properties may carry additional restrictions, usually because the comparable set supporting the income projection is too thin.
Are vacation rental loans the same as short-term rental loans?
Yes. "Vacation rental loan," "short-term rental loan," and "Airbnb loan" are used interchangeably for the same category of financing. The underwriting method and loan structure are the same regardless of the platform the property lists on or the market type. The distinction that does matter is between an investment property and a second home, which the classification section above covers.
What is the minimum credit score for a short-term rental loan?
Ridge Street's STR loans require a minimum FICO of 700. This is 40 points above the 660 minimum on our standard DSCR program for long-term rentals.
Can I use an FHA or VA loan for a short-term rental?
No. FHA and VA loans are owner-occupancy loans and cannot be used to finance an investment property. Short-term rentals are classified as investment properties by lenders, so FHA and VA programs do not apply. Short-term rental loans route through DSCR programs, conventional investment loans, or fix-and-flip financing instead.
Can I get a short-term rental loan with 10% down?
In most cases, no. STR DSCR programs cap LTV at 80% on a purchase, which requires 20% down. Fix-and-flip loans for rehab-and-rent deals accept 10% to 20% down on the purchase price, calibrated against the after-repair value, but the loan is a short-term bridge, not long-term STR financing.
What is AirbnBRRRR?
AirbnBRRRR is a variation of the traditional BRRRR strategy where investors buy, renovate, rent, refinance, and repeat using short-term rental properties instead of long-term rentals.
Does Ridge Street finance non-warrantable condos with short-term rentals?
Yes. Ridge Street finances non-warrantable condo projects, and condotels in some cases, as long as the property is cash flow positive on AirDNA projections. STR condo markets in Florida, Texas, and Colorado perform well under this program.
How many properties can I finance with a short-term rental loan at one time?
With a DSCR loan, there is no cap on the number of properties. With a conventional loan, borrowers face a DTI constraint (typically 40%) and a 10-property limit set by Fannie Mae guidelines.
Does claiming the short-term rental tax loophole affect my ability to qualify for a mortgage?
Potentially, yes. The short-term rental tax loophole can allow investors to use qualifying rental losses to offset W-2 income, which may affect how conventional lenders calculate qualifying income.
However, Fannie Mae allows lenders to add back eligible depreciation expenses when reviewing rental income on Schedule E. Other operating losses may still affect qualification, particularly for self-employed borrowers.
DSCR loans avoid this issue because lenders qualify borrowers based on the property's rental income rather than personal tax returns. Our short-term rental tax loophole guide explains how the strategy works and who can qualify.
How do I get a loan for a vacation rental property?
The process depends on how you intend to use the property and which financing program you choose.
First, confirm that local regulations allow short-term rentals at the property address. Next, determine whether the property will be used primarily as an investment or for personal stays, as this affects eligibility for STR DSCR or conventional second-home financing.
For an STR DSCR loan, lenders evaluate projected rental income using AirDNA or comparable market data. Once the property meets the program's requirements, you can submit an application with property details and your credit information.
The lender then completes the appraisal and underwriting before closing. At Ridge Street Capital, short-term rental purchase loans typically close within 21 to 25 days.
Zach Cohen is the Managing Partner of Ridge Street Capital, a direct private lender providing hard money and DSCR loans to real estate investors across 36 states. Under his leadership, the firm has funded nearly $100 million in investment property loans. He regularly works with real estate investors on rental property acquisitions, refinances, and fix-and-flip projects across the country.
Fix and Flip Loans
Funding For Purchase + Rehab
- $50,000 up to $3,000,000
- Interest Rate 10.5%-11.5%
- Origination Fee From 1.5%
- Up to 90% of Purchase and 100% of Rehab

DSCR Loans For Long Term Rentals
Perfect for first-time investors or experienced investors scaling their rental portfolio.
- Up to $2,000,000
- Interest Rates from 6.0%
- Origination Fee From 0%
- Up to 80% of LTV

DSCR Loans For Short Term Rentals
Designed for investors pursuing higher rents with a short term rental strategy.
- Up to $2,000,000
- Interest Rates from 6.25%
- Origination Fee From 0%
- Up to 80% LTV
Ready to Get Started?